Back
Leasing despite previous debt enforcement (Betreibung): What you need to know
How to remove concluded debt enforcement records from the debt register in Switzerland, improve your creditworthiness with ZEK and CRIF, and increase your chances of getting a leasing. Let’s go.
15th September 2023
Leasing despite debt enforcement is only possible in Switzerland if the case has been settled and removed from your debt enforcement register. An active debt enforcement will generally prevent you from getting a leasing with reputable providers. This applies to Gowago as well as to other reputable providers.
The reason is regulated by law: A leasing or loan must not be granted if it could lead to a risk of over-indebtedness.
The good news: You’re not stuck. Unjustified debt enforcements can be challenged, and paid ones can be removed from the register through the relevant debt enforcement office. Once your record is cleared, you can apply for a leasing again.
In this article, we explain key terms such as debt enforcement, creditworthiness, ZEK, CRIF, and Intrum, and show you step by step how to clean up your record — and clear the way for your next car. Let’s Go.
The most important terms you need to know
| Term | Description |
|---|---|
| Debt Enforcement / “Betreibung” | In Switzerland, a debt enforcement or “Betreibung” is the legal process used to recover outstanding debts owed by a debtor to a creditor. |
| Debt Enforcement Register | A place for information about debt enforcement proceedings. A debt enforcement remains visible in the register for five years, even if it was contested. |
| Creditor | A "creditor" is an individual or institution with a claim against a debtor. |
| Debtor | A "debtor" is an individual or entity financially or contractually obligated to a creditor. |
| Legal Objection | A "legal objection" is a formal means to contest a debt enforcement in Switzerland. |
| ZEK | The ZEK (Central Office for Credit Information) records creditworthiness information from credit transactions in Switzerland for both individuals and legal entities. |
| CRIF | A credit reporting agency in Switzerland that provides credit-relevant information about individuals and businesses. Individuals can also request a self-disclosure report (Selbstauskunft) here. |
| Intrum | A European debt collection agency offering debt management and payment services for creditors. gowago.ch collaborates with Intrum for the online signature process. |
- The most important terms you need to know
- Can I get a leasing while I have running debt enforcements?
- What is a Debt Enforcement?
- Companies Offering Leases with Active Debt Enforcement Proceedings
- Securing a Trustworthy Lease Despite a Debt Enforcement
- How can I get rid of a debt enforcement?
- How Do I Know If I Have a Debt Enforcement?
- Conclusion on Debt Enforcement Proceedings and Leasing
Can I get a leasing while I have running debt enforcements?
In general, you cannot get a leasing in Switzerland if you have an active debt enforcement. A key requirement for leasing is that you are in a financially stable situation — and a debt enforcement indicates the opposite. You can still apply, but with a reputable, transparent bank your chances of approval are slim.
When you apply for a leasing, the bank will first assess your creditworthiness. This is primarily for consumer protection. The goal is to ensure that you do not take on debt you cannot afford. In Switzerland, financial institutions are legally prohibited from granting credit if it could lead to over-indebtedness. The UWG (Art. 3 para. 1 let. n) points this out as well:
"The granting of credit is prohibited if it leads to the over-indebtedness of the consumer."
If a bank knowingly grants you credit (including a lease) that pushes you into debt, it is acting unlawfully — quite apart from the fact that the bank may lose income if your lease goes unpaid.
A credit check means that the bank evaluates whether you have sufficient financial means for a leasing. To do so, it will consult credit agencies such as CRIF or ZEK to assess your financial situation.
Why can’t you get a leasing with a debt enforcement? Because a debt enforcement means you are, in theory, already in the negative. In other words, you are already in debt and should not take on additional financial obligations.
However, there is a solution: you can resolve the debt enforcement by paying off your debts and requesting its removal from the debt enforcement register. Once it is cleared, you are no longer considered indebted. If the debt enforcement was unjustified, you can also have it deleted.
What is a Debt Enforcement?
In Switzerland, the process of debt recovery is termed "debt enforcement." It's a legal tool allowing creditors to claim their outstanding debts from defaulting debtors. The process is structured, transparent, and offers both parties a fair opportunity to present their case. Let's delve deeper into the debt enforcement procedure.
Initiation of Debt Enforcement
The first step is to submit a debt enforcement request to the debt enforcement office responsible for the debtor's place of residence. This request must include details about the creditor and the debtor, including the amount owed in Swiss currency. It's crucial to note that no additional documents should be attached, except the basis for the claim.
The debt enforcement office reviews the request for its formality, not the validity of the claim. This means they don't verify the legitimacy of the debt but only ensure the request was properly filed. Unfortunately, this means unjustified debt enforcement proceedings are a reality in Switzerland - theoretically, anyone can initiate a debt enforcement against anyone else.
Post-Initiation Procedures
Once the debt enforcement request is filed, the debt enforcement office issues a payment order. This is delivered to the debtor, who then has 20 days to settle the debt. If the debtor fails to pay, they can raise a legal objection within 10 days. Such an objection halts the debt enforcement process unless the creditor can legally enforce their claim.
It's essential to note that an unjustified legal objection can incur significant costs. Therefore, debtors should ensure they have a valid reason for the objection.
Costs Associated with Debt Enforcement
Typically, the debtor bears the costs of the debt enforcement process. This includes the fee for a payment order. However, additional costs may arise for delivery attempts and other procedural steps.
Companies Offering Leases with Active Debt Enforcement Proceedings
Some companies claim to offer lease contracts for individuals with debt enforcement proceedings. While this might seem tempting at first glance, there are crucial considerations:
- Too Good to Be True: If an offer sounds too good, it probably is. Companies offering leases to those with poor credit might have hidden fees, exorbitant interest rates, and unfavorable contract terms.
- Lack of Transparency: Some of these companies might not be transparent about their offer's conditions. It's vital to scrutinize all contract details and ensure you understand every aspect. In the past, certain companies offered leases with debt enforcement proceedings but only rented out the car.
- Company Reputation: It's advisable to check the company's reputation before signing any contract. Online reviews, customer feedback, and recommendations can provide insights into the company's trustworthiness.
Securing a Trustworthy Lease Despite a Debt Enforcement
We recommend applying for a lease only if you have a clean financial record, meaning no active debt enforcement proceedings. Having 2-3 settled debt enforcement proceedings on your record might not be a significant issue. However, if there are more, you should address them promptly. Debt collections can hinder not only lease applications but also house hunting, other credit applications, and even job searches. But don't worry, there are ways to address debt enforcement proceedings.
How can I get rid of a debt enforcement?
Settling the Debt Enforcement
The most straightforward method to address a debt enforcement is to settle the debt. You can pay the entire amount within the specified period in the payment order. Once paid, the debt enforcement process ends.
However, be cautious: The debt enforcement isn't automatically removed, even if settled. Without your intervention, it remains on your record for five years, even after payment, legal objection, or if it was unjustified. Only then is the entry automatically removed.
If you settle the debt enforcement, it's noted in the debt enforcement register as "debt enforcement paid to the debt enforcement office." It's up to the bank to decide if they'll grant you a lease with settled debt enforcement proceedings. 2-3 settled debt enforcement proceedings in the past might be acceptable, but numerous debt enforcement proceedings will likely pose challenges, as trust in your financial capability might be compromised.
Removing the Debt Enforcement
If you believe the debt enforcement is unjustified or if you've already settled the debt, you can request its removal.
- Proof of Payment: If you settled the debt before the debt enforcement was initiated, you can prove this with payment receipts or bank statements. It's possible that your payment and the payment order crossed paths. In such cases, you must contest the debt enforcement at the debt enforcement office within 10 days. It's crucial to retain proof of your payments, so always keep your payment receipts and invoices.
- Agreement with the Creditor: In some instances, you can directly negotiate with the creditor and request them to withdraw the debt enforcement. This is common when misunderstandings or errors occur. The creditor will then process the withdrawal at the debt enforcement office. But be wary! The creditor isn't obligated to process your removal request.
- Legal Action: You can also contest the debt enforcement legally. If the court rules in your favor, they'll annul the debt enforcement. However, be aware that legal proceedings can incur court and attorney fees. In such cases, it's advisable to consult an attorney.
Can I contest the debt enforcement?
If you believe the debt enforcement is unjustified, you can contest it:
- Legal Objection (Rechtsvorschlag): Within 10 days of receiving the payment order, you can raise a legal objection at the debt enforcement office, orally or in writing. You do not have to give reasons. The legal objection temporarily halts the debt enforcement process, and the creditor must then go to court to have it set aside.
- Legal Proceedings: If the creditor contests the legal objection, a legal proceeding is initiated. Here, you have the opportunity to present your arguments and evidence. The court then decides whether to continue or annul the debt enforcement.
Unjustified Debt Enforcement
In Switzerland, anyone can initiate a debt enforcement against anyone else without any prerequisites. This means someone can start a debt enforcement against another individual without having to prove an actual debt exists. This system can lead to unjustified debt enforcement proceedings.
Characteristics of an Unjustified Debt Enforcement:
- No Actual Debt: The debtor doesn't owe the creditor any money, or the claim is disputed.
- Lack of Contractual Basis: There's no legal or contractual basis for the claim, such as hidden costs in an ostensibly free online offer.
- System Abuse: Sometimes, creditors exploit the debt enforcement system to pressure debtors, even when no genuine claim exists.
Protection Against Unjustified Debt Enforcement Proceedings:
Since January 1, 2019, Swiss law offers those unjustly subjected to debt enforcement proceedings a tool to clean their debt enforcement register. They can request the debt enforcement office not to disclose the unjustified debt enforcement. This procedure costs a flat fee of 40 Swiss Francs.
Contesting an Unjustified Debt Enforcement:
Raise a legal objection within 10 days of receiving the payment order (see above). This halts the debt enforcement process for the time being.
Three months after the payment order was delivered, you can file a "Request for Non-Disclosure of a Debt Enforcement to Third Parties" at the debt enforcement office. Following this procedure, the debt enforcement isn't removed but won't appear in extracts from the debt enforcement register.
How Do I Know If I Have a Debt Enforcement?
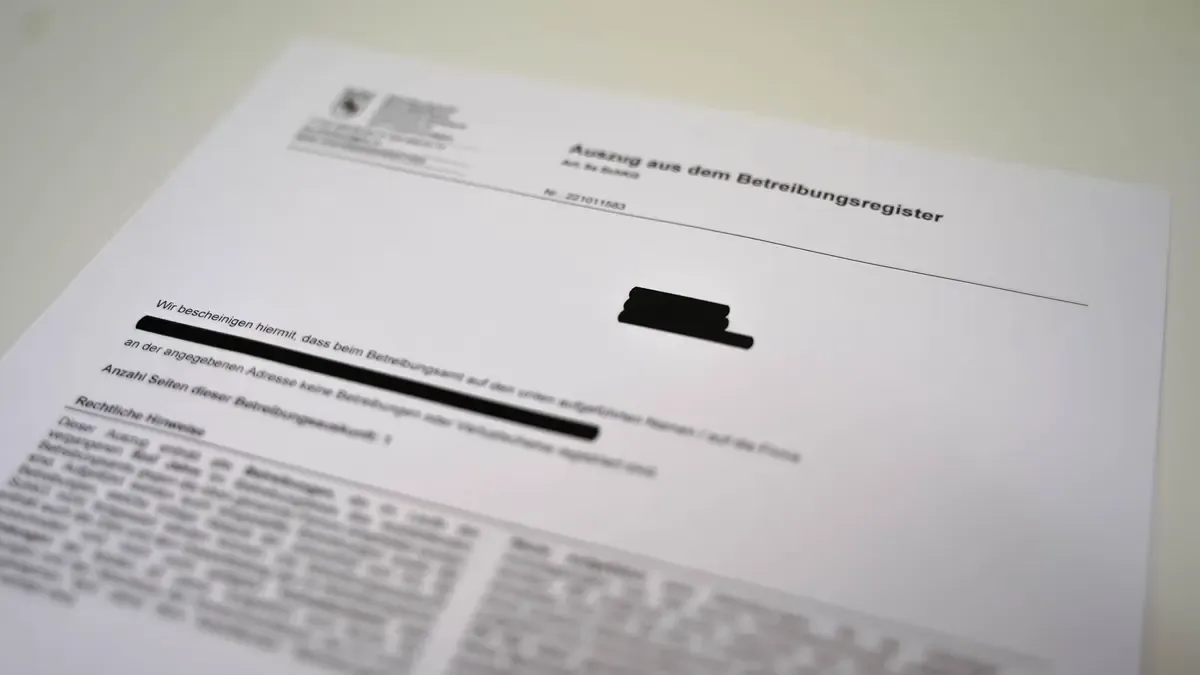
You can see whether a debt enforcement is registered against you in a debt enforcement register extract. You order it from the debt enforcement office at your place of residence, in many cantons also online or at the counter. The extract shows whether a debt enforcement was initiated against you in the last five years. You can also request a self-disclosure report (Selbstauskunft) from credit agencies such as CRIF. Which organisations exist and what they do is explained in the next section.
ZEK, CRIF, and Intrum: An Overview and Comparison
In Switzerland, various organisations deal with credit information and debt collection. Three of the most renowned are ZEK, CRIF, and Intrum. In this article, we'll provide an in-depth look at each of these organisations and compare them.
ZEK (Central Office for Credit Information)
Description: The ZEK, also known as the Central Office for Credit Information, is an organization that gathers information about credit obligations of individuals and businesses in Switzerland. It serves as a central hub for lenders to check the creditworthiness of applicants.
Main Tasks:
- Collecting and storing credit information.
- Providing this information to banks and other financial institutions.
- Ensuring the correct and fair use of credit data.
Check out ZEK's website and details here.
CRIF
Description: CRIF is an international company specialising in credit reporting, business information, and credit solutions. In Switzerland, CRIF offers credit checking and rating services.
Main Tasks:
- Creating credit reports for individuals and businesses.
- Assisting businesses in risk assessment and decision-making.
- Offering data analysis and management solutions.
You can also have CRIF give you an overview of your creditworthiness. Click here to request a self-disclosure report.
Intrum
Description: Intrum is a leading European company in Credit Management Services. It offers a wide range of services, from invoicing to debt collection and debt purchasing.
Main Tasks:
- Assisting businesses in invoicing and debt management.
- Conducting debt collection services for unpaid invoices.
- Purchasing debt portfolios from businesses.
gowago.ch collaborates closely with Intrum to simplify the leasing process. For instance, all online signatures for leasing contracts with gowago.ch are processed in conjunction with Intrum.
Comparison of the Three Organisations
- Purpose: While ZEK and CRIF primarily gather and provide credit information, Intrum focuses on debt management and collection.
- Services: ZEK mainly focuses on collecting and providing credit information. CRIF offers a broader range of services, including data analysis and risk assessment. Intrum provides comprehensive services in the realm of debt management.
Conclusion on Debt Enforcement Proceedings and Leasing
In Switzerland, the debt enforcement system is an efficient means of debt recovery. But like any system, there are pitfalls and potential abuses. An unjustified debt enforcement can have significant negative impacts on an individual's life and creditworthiness. Therefore, it's crucial to be aware of one's rights and responsibilities. Organisations like ZEK, CRIF, and Intrum play a vital role in assessing creditworthiness, and it's essential to understand their functions and differences. If faced with a debt enforcement, whether justified or not, it's advisable to get informed promptly and, if necessary, seek legal advice. Knowing the various ways to combat, pay, or remove a debt enforcement is a valuable tool to ensure financial clarity and security in Switzerland.